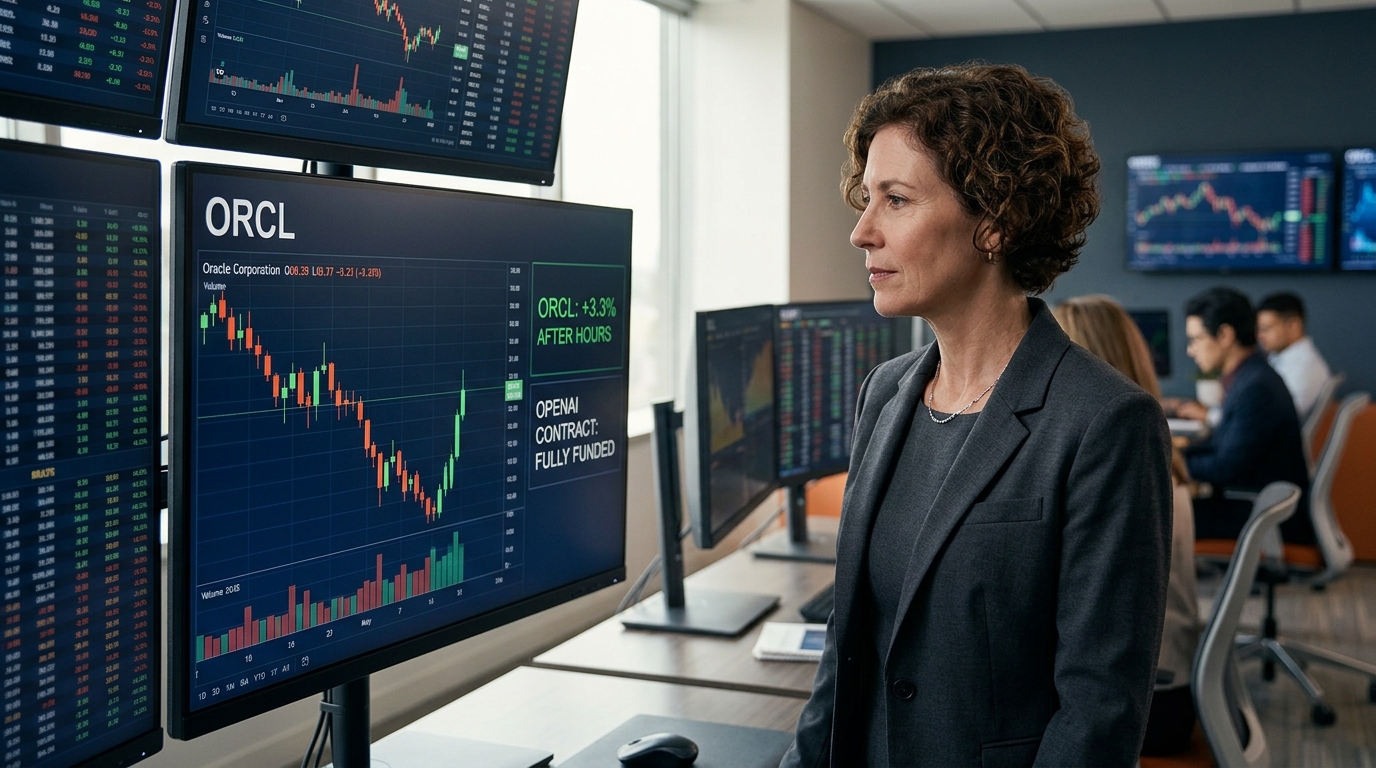
Oracle dropped to a fresh 52-week low on Friday, closing at $101.19, before the company made the announcement that sent shares up 3.3% after hours. Oracle said its infrastructure contract with OpenAI is fully funded following a final capital raise earlier this month. The timing is worth sitting with: the stock hit a new floor, then the company removed the question that had been driving it there.
The raise totaled $20 billion, split between roughly $10 billion in equity and $10 billion in debt. Oracle described itself as the first hyperscaler fully funded for the current AI investment cycle. That framing matters. The concentrated risk embedded in a single OpenAI contract had become the central argument for avoiding ORCL, and Oracle just answered it directly.
The Business
Oracle’s cloud infrastructure segment is growing faster than almost any large-cap technology company in the market. Cloud infrastructure revenue rose 121% in Q1 FY27, reaching $7.4 billion. Oracle booked more than $30 billion of additional AI cloud contracts in Q1, increasing its remaining performance obligations to $664 billion. Those are not speculative pipeline figures. They are signed commitments.
Market observers had focused on balance sheet leverage and customer concentration risk tied to its OpenAI relationship, which Oracle has said is driving a significant portion of its infrastructure build-out. That concern kept institutional capital on the sidelines even as the underlying revenue growth accelerated. Friday’s statement does not dissolve the risk entirely, but it eliminates the most immediate version of it.
Why Wall Street Is Paying Attention
Oracle added that its ability to deliver on the OpenAI contract does not depend on further vendor discussions, framing any continuing talks with suppliers as optional rather than necessary. It had pledged at its investor day to cap additional capital-markets fundraising for fiscal 2027 through fiscal 2030 at $20 billion, divided evenly between equity and gross debt, excluding refinancing. That cap is now reached. The capital raise question is closed.
Construction progress adds conviction. The Abilene, Texas campus, where Oracle says Astra-6 was trained, is nearly complete. The next gigawatt-scale site in Shackelford County, Texas, has received full permitting. Oracle also says delivery timelines for Nvidia’s Vera Rubin systems remain on track for the coming weeks. Oracle is building, not just promising.
What’s Driving the Opportunity
Oracle set a fiscal 2029 free cash flow target of more than $30 billion, after negative $23.7 billion in fiscal 2026. Oracle has said it expects to self-fund future growth beginning in fiscal 2029. Total revenue growth of more than 35% CAGR from FY26 through FY30 is expected, reaching $225 billion or more in FY30. Against a stock sitting near $101 at Friday’s close, the forward price-to-earnings multiple has compressed to levels that look difficult to justify even under conservative delivery assumptions.
The PE ratio sits near 15.87 on trailing earnings. The average analyst 12-month price target among 42 analysts stands at $236.18. That is more than a double from where the stock closed Friday.
What Could Go Wrong
Funded does not mean delivered. Oracle’s investor day plan leans on mechanisms such as vendor financing and customer prepayments, so “fully funded” describes the financing in place today and not every operational risk in the build still to come. OpenAI’s own ability to sustain payments across a multi-year commitment carries credit risk that no single statement can eliminate. Free cash flow remains deeply negative through fiscal 2026 and management has said it does not expect to self-fund future growth until fiscal 2029, which means execution risk is real and long-dated. Any slip in rack delivery timelines, permitting delays, or a weakening in OpenAI’s financial capacity would reopen the debate quickly.
Oracle dropped to $101.19 on Friday, undercutting its prior 52-week low of $109.21 and sitting far below its 52-week high of $250.25. The stock is not cheap because nobody has noticed. It is cheap because the funding question was unresolved and the balance sheet was leveraged during peak capital spending. Friday’s announcement closes the first part of that argument.
The Bottom Line
Among large-cap technology names today, Oracle offers a combination that is genuinely unusual: revenue accelerating at triple-digit rates in its core infrastructure segment, a $664 billion contract backlog, and a stock about 60% off its peak. The funding announcement reframes the central risk the market had been pricing. It does not eliminate execution risk, and Oracle has said it does not expect to self-fund future growth until fiscal 2029. But the counterparty question that defined the selloff now has a clear, public answer. That changes the risk-reward calculation, and at $101 it is worth taking seriously.