10:00am ET. That is the only time that matters this morning. The University of Michigan releases its October preliminary consumer sentiment reading, and the setup heading into it is uncomfortable. The October preliminary comes out Friday, October 9, 2026 at 10:00am ET, with a consensus of 47.6 against September’s final of 48.1. That leaves sentiment just 2.8 points above its all-time low.
The all-time low is 44.8, set in the final May 2026 reading, the worst result in a data series running back to 1952, sliding from 49.8 in April 2026. This is not ancient history. It was five months ago, and the conditions that drove it have not resolved.
Why the Inflation Line Matters More
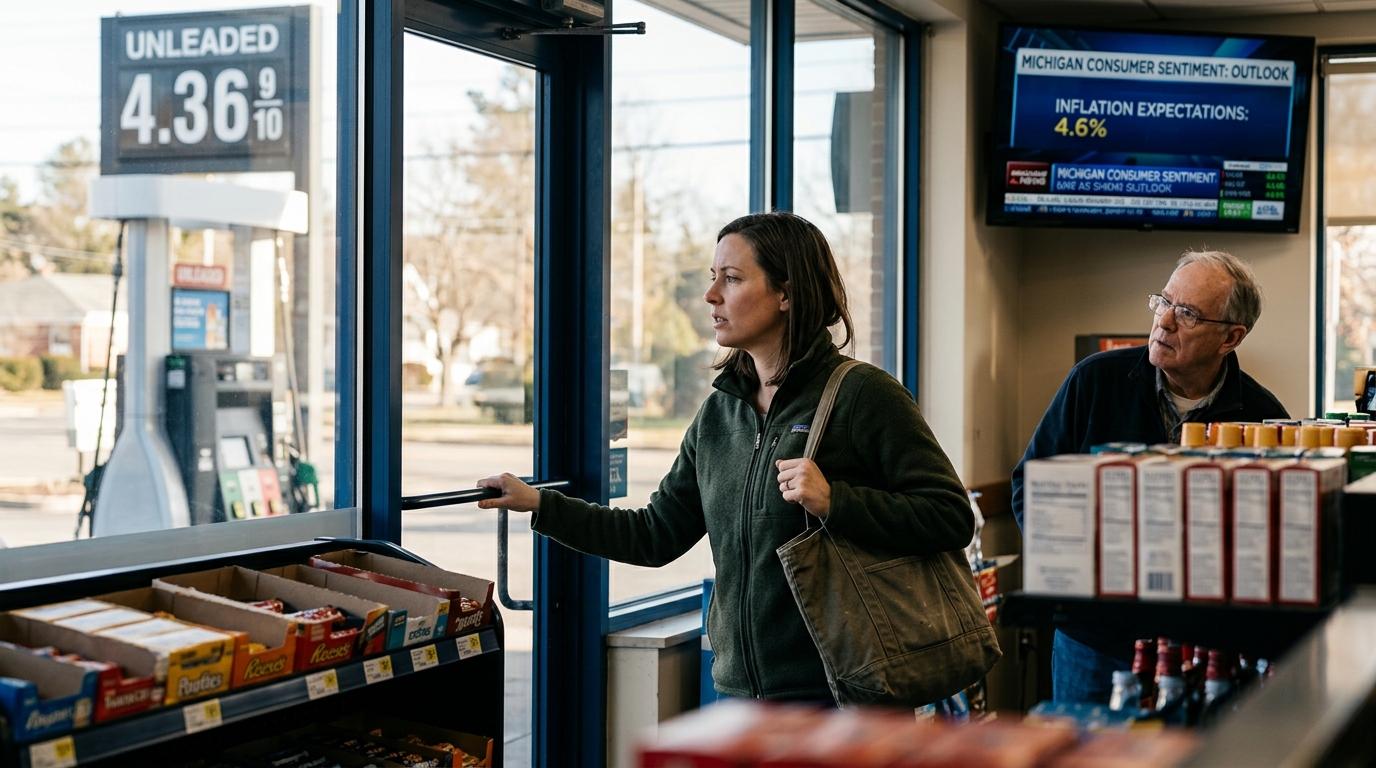
Year-ahead inflation expectations may draw as much attention as the headline this time. They jumped to 4.6% in September. Rising inflation expectations are watched closely by the Federal Reserve, since expectations themselves can become self-reinforcing if consumers and businesses begin adjusting behavior based on anticipated future price increases.
The fuel backdrop during the October survey window was not friendly. Gas prices remain the highest they have ever been for this time of year. The national average dropped 5 cents this past week to $4.36. The average U.S. gas price was about $4.37 per gallon on October 6. Brent crude, the global benchmark that flows through into pump costs, was trading above $104 per barrel in the latest session.
U.S. gas prices were higher during the October survey window than during the September one, which means the pressure on the inflation expectations figure was skewed to the upside before a single respondent picked up the phone.
What to Watch in Retail
The release lands directly on the stocks most sensitive to consumer mood. XRT, the SPDR S&P Retail ETF, was trading around $82.63 heading into the week, sitting below its 50-day and 200-day moving averages. The ETF tracks an equal-weighted basket of roughly 75 retailers and reflects the breadth of consumer spending, not just the mega-cap names that can hide sector stress.
Within retail, the divergence between WMT and TGT has been the defining trade of 2026. Year-to-date, Walmart is slightly down to roughly flat, while Target is sharply higher. Target posted a 21.1% stock gain in the third quarter, standing out in a consumer sector that declined about 3% overall, a move reflecting a pivot toward value-conscious spending despite inflationary pressures. As consumers become more cautious, lower prices could help Target attract more shoppers and support traffic during the critical holiday period. Walmart, meanwhile, trades at roughly 40 times earnings, a valuation that prices in continued traffic from budget-constrained households but leaves no room for a demand miss.
The Risk Either Way
A headline print below 47 would put the index within striking distance of the May record low and likely pressure XRT, discretionary names, and any retailer without a clear value proposition. A bounce above 48.5 could spark a short-covering move in beaten-down retail, but the inflation expectations component would still need to come in below 4.6% to give the Fed any comfort.
The short-term outlook for business conditions has deteriorated sharply amid renewed concerns that elevated fuel prices and escalating trade disputes could weigh on the broader economy. That backdrop does not disappear with one data point. What changes at 10:00am is the market’s read on how much worse it has gotten.
The Cheat Sheet
- Top Theme: Consumer confidence is hanging near its lowest level in 74 years of survey history, with fuel costs keeping inflation expectations elevated.
- Stock to Watch: XRT. An equal-weighted retail ETF sitting below both its 50- and 200-day averages is the cleanest vehicle to trade the sentiment reaction in either direction.
- Sector to Watch: Consumer discretionary. The gap between value retailers and specialty/discretionary names widens or narrows depending on whether today’s print signals demand destruction or stabilization.
- Biggest Risk: Inflation expectations print above 4.6%. That figure, not the headline index, is what the Fed is watching and what could shift rate expectations into the October 14 CPI release.
- One Thing to Remember: The consensus is 47.6. The record low is 44.8. There is more room to the downside than the upside, and the gas price data collected during the survey window was worse than September’s.