There is a specific kind of capital allocation decision that separates the merely ambitious from the genuinely contrarian. Masayoshi Son appears to have made one. SoftBank is considering an acquisition of Allied Universal, the largest security services company in the United States, as Son explores ways to deploy AI-powered robots across industries. The reported equity value is as much as $18 billion. Include Allied’s obligations and the total picture is larger: the security company has about $12 billion of publicly traded debt, across loans and bonds.
The surface reading of this deal is straightforward. The deeper one is not.
Why This Business Matters
Allied Universal is a trusted partner to more than 400 of the Fortune 500, with operations in over 100 countries and territories. It is the third-largest private employer in North America and seventh in the world, with annual revenue of approximately $23 billion. Its contracts span guard staffing for businesses and events, specialized protection including canine teams and bomb technicians, subway security for New York City’s Metropolitan Transportation Authority, and a sizable role safeguarding data center projects.
That last point matters. SoftBank has bet heavily on AI, and AI runs on data centers. Those facilities need physical protection, and Allied already provides support in that segment. Son is not simply buying a workforce; he is acquiring a customer base embedded in the infrastructure his other bets depend on.
The Mogul Mindset
The structure of the opportunity echoes a principle Charlie Munger articulated often: the best businesses are ones where the economics improve as they scale. Son’s reported logic goes further. Owning the business that performs security tasks would give SoftBank a built-in customer and a real-world laboratory. Instead of selling robots to security firms, it would be the security firm.
SoftBank has increasingly concentrated its investment strategy on AI infrastructure, including a $64 billion commitment to OpenAI, data center development and semiconductor designer Arm Holdings. The conglomerate also agreed last year to acquire the robotics business of Swiss engineering group ABB for approximately $5.4 billion. Allied Universal would be the deployment layer that turns those upstream bets into operational reality.
What Makes This Compelling, and What Could Go Wrong
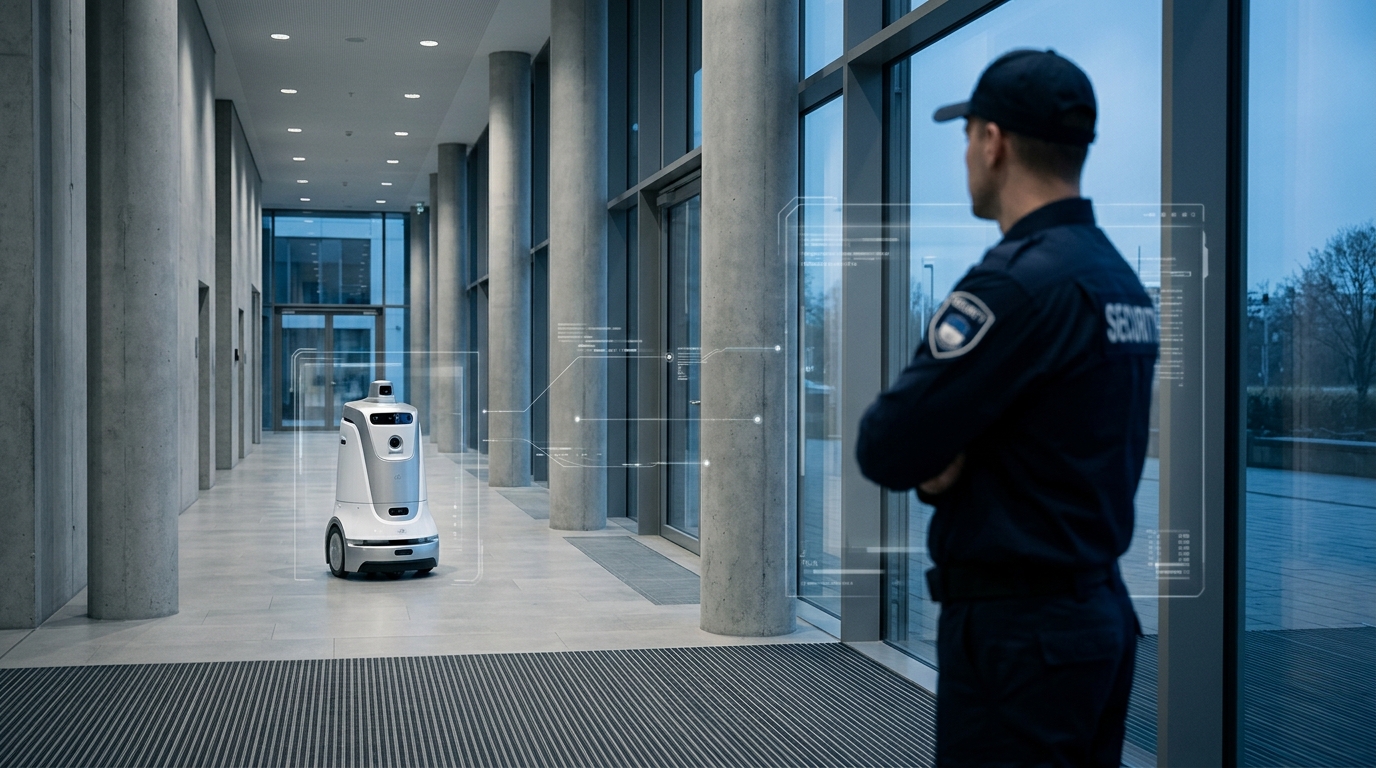
With Allied, SoftBank would look to eventually replace some staff with robots for certain security tasks, though the deployment of humanoid security workers is likely to take longer. That admission is crucial. The automation thesis is a long-duration one, and Son is paying a present-day price for a future-state business. Allied has already been testing its own automation, including a five-foot-tall, 300-pound autonomous patrol unit, but closing the gap between a prototype on patrol and a scaled replacement for hundreds of thousands of workers is a challenge of a different magnitude.
The balance sheet deserves equal scrutiny. A transaction with an enterprise value that could near $30 billion, layered on top of a $30 billion OpenAI commitment, raises reasonable questions about how much capital SoftBank is tying up in long-dated bets. Warburg Pincus and Canadian pension fund La Caisse currently back Allied Universal, and any deal would need to satisfy sellers who know exactly what the business is worth as a steady-state labor operation, not merely as a robotics proving ground.
The Long-Term Verdict
The move is either Son’s most disciplined thesis yet or his most expensive leap of faith. Buying the distribution channel for your own technology before that technology is proven is a bold sequence. But history rewards investors who secure the deployment infrastructure early, before the economics are obvious to everyone. Son has long expressed the view that AI-powered robots will help address labor shortages and replace human work across a wide range of service sectors, including security, cleaning, and logistics. Allied Universal would convert that conviction into a contractual obligation to deliver. That is either a forcing function for innovation or a $30 billion anchor. Disciplined long-term investors will want clarity on the robotics timeline before treating this as the former.