While Workday has lost 33% this year and Oracle briefly shed nearly 9% in a single session last Wednesday on hotter-than-expected CPI data, SAP has dropped a comparatively modest 7.7% from its January open. That relative resilience looks like a claim worth testing. Wednesday’s Q3 report is where the test happens.
Why This Stock Now
The U.S. enterprise software sector is in freefall. Salesforce is down 30% year-to-date. The software ETF IGV has shed roughly 23%. In that wreckage, SAP’s smaller decline makes it look like the last standing large-cap AI software idea in the developed world. But investors shopping beaten-down software names need to answer a harder question: is SAP genuinely more durable, or simply later to crack?
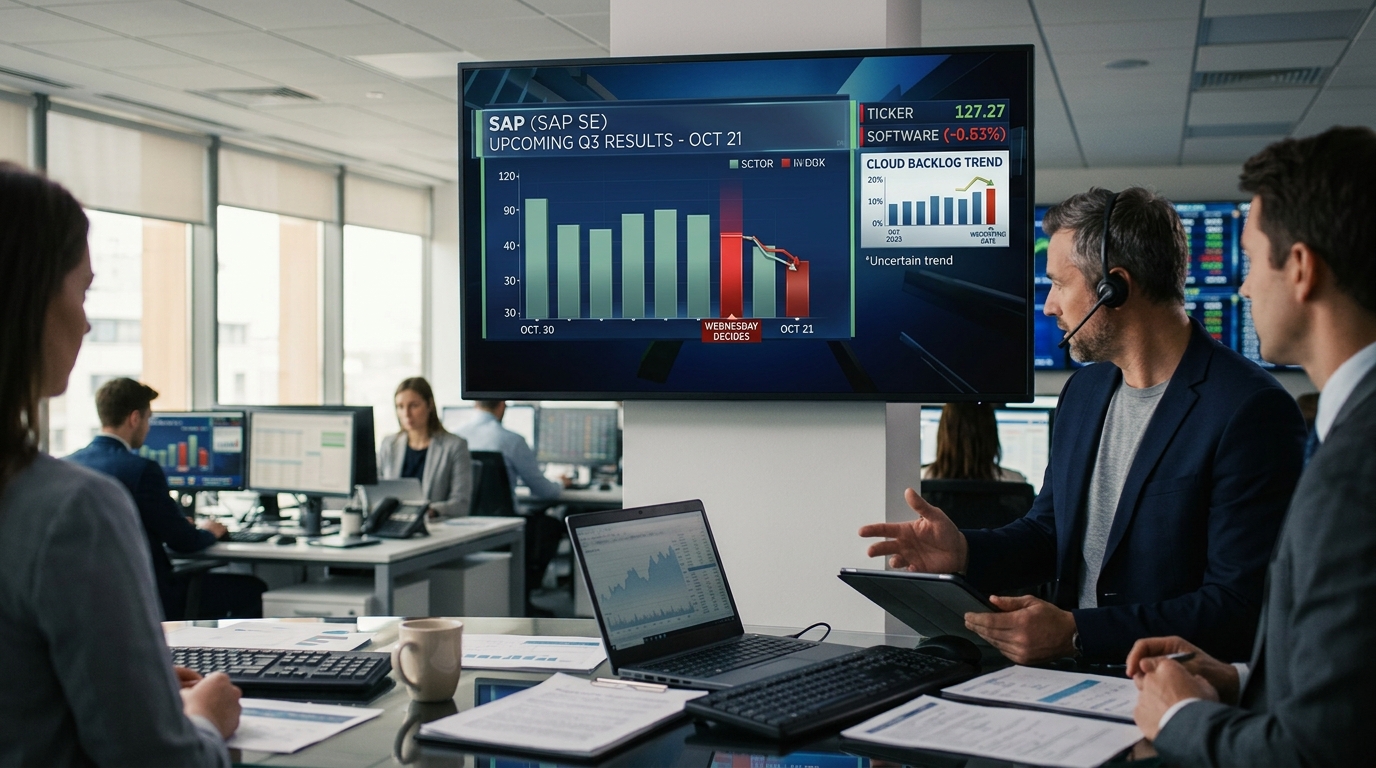
Wednesday settles part of that. Analysts expect $2.04 per share on $11.45 billion in revenue. Those numbers matter less than what sits behind them: the current cloud backlog figure, which measures contracted cloud revenue SAP expects to recognize over the next 12 months. In Q2 that number was €22.9 billion, up 26% at constant currencies. If Q3 shows acceleration, the AI product story gets real financial scaffolding. If it slips, the product blitz looks like noise.
The Business
SAP is the world’s largest provider of enterprise resource planning software, embedded in the financial and operational processes of more than 400,000 customers across 180 countries. That installed base is the moat. Switching costs in ERP are among the highest in software, which is why SAP can run a cloud migration at scale and call the backlog growth a leading indicator rather than a wish.
The AI layer being built on top of that base is called Joule. At SAP Connect in Las Vegas in early October, the company launched Joule Work, a natural-language interface letting employees delegate tasks to AI agents across SAP and third-party data. SAP says Joule Work is already in use with its own 110,000 employees. General availability for customers began in October. SAP also launched SAP Pay, now generally available in the U.S. and U.K., embedded directly in Cloud ERP. Both moves extend monetization inside the existing customer base rather than requiring SAP to win new logos to grow revenue.
Why Wall Street Is Paying Attention
TD Cowen raised its price target from $205 to $250 on October 15, citing a GSI analysis that flagged a second consecutive quarter of above-average cloud migration growth, as delayed ERP projects resumed. Wells Fargo issued a Buy rating. BMO Capital raised its target from $177 to $235. The bulls are stacking up. JPMorgan stayed at Neutral, with analyst Toby Ogg noting elevated market expectations heading into the Q3 report and asking whether the 2026 and 2027 outlook adequately justifies buying at current levels.
That split is the honest map of the situation. The company also announced the TechWolf acquisition on October 6, a Belgian AI firm that infers workforce skills from existing enterprise data, expected to close in Q4 2026. It deepens the SuccessFactors HR portfolio and gives Joule a skills intelligence layer. Financial terms were not disclosed.
What’s Driving the Opportunity
SAP’s Q2 earnings miss was real. Adjusted EPS came in at $1.82 against a $2.03 consensus, and revenue at $11.28 billion fell short of the $11.44 billion forecast. But cloud revenue still rose 24% at constant currencies in that quarter, Cloud ERP Suite revenue grew 27%, and AI was present in more than 90% of SAP’s 50 largest deals. The miss was on profitability, partly from acquisition costs tied to Dremio and Prior Labs. The underlying demand signal was intact.
That is the precise reason Wednesday’s cloud backlog figure carries so much weight. Q2’s 26% growth held steady despite the headline miss. If Q3 shows 27% or better, SAP’s AI strategy is generating contracted future revenue, not just keynote slides. SAP is also running a share buyback program, which at minimum signals a willingness to return capital even as it leans into AI investment.
What Could Go Wrong
The valuation is the first problem. At roughly 29 times normalized earnings, SAP carries a significant premium to Oracle at 16 times and Workday at 19 times. That premium assumes the cloud backlog keeps growing and AI monetization accelerates. A deceleration in backlog growth, from 26% to something in the low 20s, would likely compress the multiple fast.
Second, the product rollout timeline is genuinely stretched. Most of the new Joule agent capabilities highlighted at SAP Connect do not reach general availability until Q4 2026 or Q1 2027. TechWolf has not closed. SAP Pay is live but new. The company is selling a pipeline, and this market is punishing AI stories that can’t show cash. A Munich court ruling against SAP’s Signavio unit on patent grounds adds a litigation overhang whose cost isn’t yet quantified.
The Bottom Line
Against a field of U.S. software names that are already deeply discounted, SAP’s lesser decline might look like crowding rather than quality. But the backlog dynamic is meaningfully different. A company with €22.9 billion of contracted cloud revenue under management is not the same risk as a pure-play SaaS vendor losing seat counts to AI-native alternatives. SAP’s installed base and switching costs give Wednesday’s number real predictive power.
If the Q3 cloud backlog holds or accelerates above 26%, SAP is the one large AI software stock where the product announcements have a plausible path to the income statement. That is a narrower claim than the bulls are making, but it is the right one to make today.