There is a question worth asking every time an enterprise software company posts strong numbers: is this growth, or is it gravity? For SAP, the answer is increasingly both.
The company crossed €10 billion in quarterly revenue for the first time in Q3 2026, reaching €10.3 billion, up 12% year over year. Current cloud backlog, a measure of contracted future revenue, reached €24.1 billion, up 26% from a year earlier at constant currencies. Adjusted earnings per share of $2.14 beat the consensus estimate of $2.04 by about 5%.
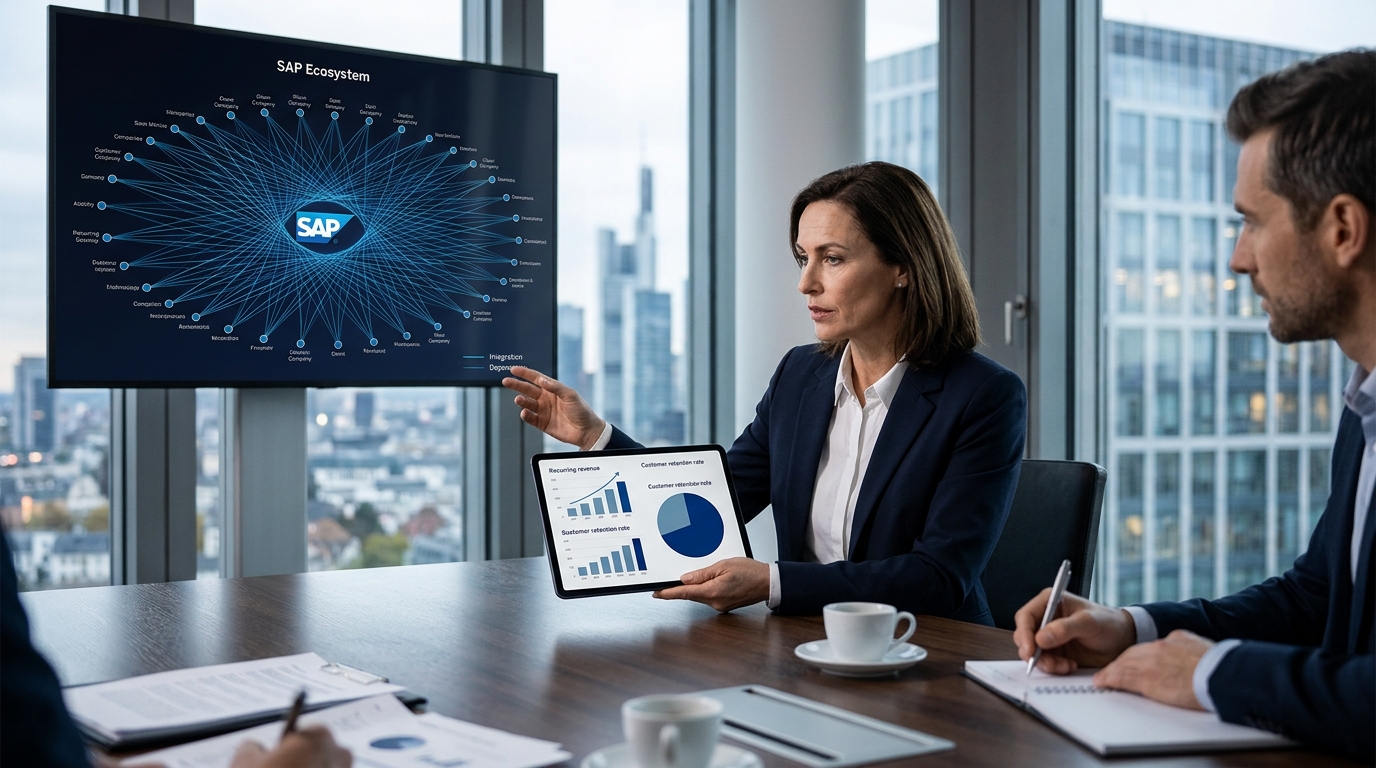
Cloud ERP Suite revenue rose 28% at constant currencies and now accounts for the vast majority of total cloud revenue. That concentration matters. SAP’s ERP suite is where payroll runs, where supply chains are managed, where financial closes happen. Companies do not swap it out the way they might swap a marketing tool or a project management platform. The switching costs are not financial in the normal sense; they are organizational. Ripping out SAP means retraining tens of thousands of people, rebuilding integrations, and accepting years of operational risk. Most enterprises simply do not.
The AI Disintermediation Question
The fashionable worry about SAP is that artificial intelligence will allow new competitors to replicate its functionality faster and cheaper, commoditizing what once looked like a durable moat. The bigger debate around SAP is whether AI weakens traditional SaaS businesses, but the contrarian case holds that it does the opposite. SAP’s key competitive advantage lies not just in owning enterprise data, but in understanding the business meaning and relationships behind that data.
That distinction is important. An AI model trained on generic data cannot tell a retailer’s procurement system what a particular part number means in the context of that company’s supplier contracts. SAP can. SAP’s core moat, comprising ERP data, process semantics, and compliance controls, makes it more defensible than front-end tools or workflow vendors. Challengers building AI-native competitors are arriving at the application layer. SAP sits deeper, at the data and process layer where the decisions are actually made.
Governance is becoming the new moat. SAP’s positioning of its Business AI Platform as an architecture story reflects a strategic read on enterprise buying behavior: CIOs and compliance officers now view AI governance, auditability, and policy enforcement as more valuable than incremental productivity gains from additional copilots. That is a positioning an upstart cannot easily replicate.
Capital Returned, Risks Acknowledged
As of September 30, 2026, SAP had repurchased 25.2 million shares at an average price of €164.79, totaling approximately €4.2 billion under its buyback program. The broader repurchase program announced in January 2026 targets up to €10 billion through December 31, 2027. For a company with an approximately €10 billion free cash flow target for 2026, that level of return is credible rather than aspirational.
The risks deserve direct treatment. Management expects cloud revenue growth for full-year 2026 to land at the upper end of its range, implying 23% to 25% growth at constant currencies. It also expects current cloud backlog growth at constant currencies to slightly decelerate. Investors willing to pay a premium multiple for SAP need to believe the backlog converts reliably and that AI consumption revenue accelerates as the base matures.
The Long-Term Verdict
SAP is not a cheap stock, and it is not supposed to be. It is a business that global enterprises have embedded so deeply that replacing it is a multi-year, multi-billion-dollar undertaking. SAP remains mission-critical for customers who want to fundamentally change the way they do work through AI. That stickiness is the investment case, and the Q3 numbers show it compounding rather than eroding. The enterprise AI era is more likely to expand SAP’s relevance than to threaten it.