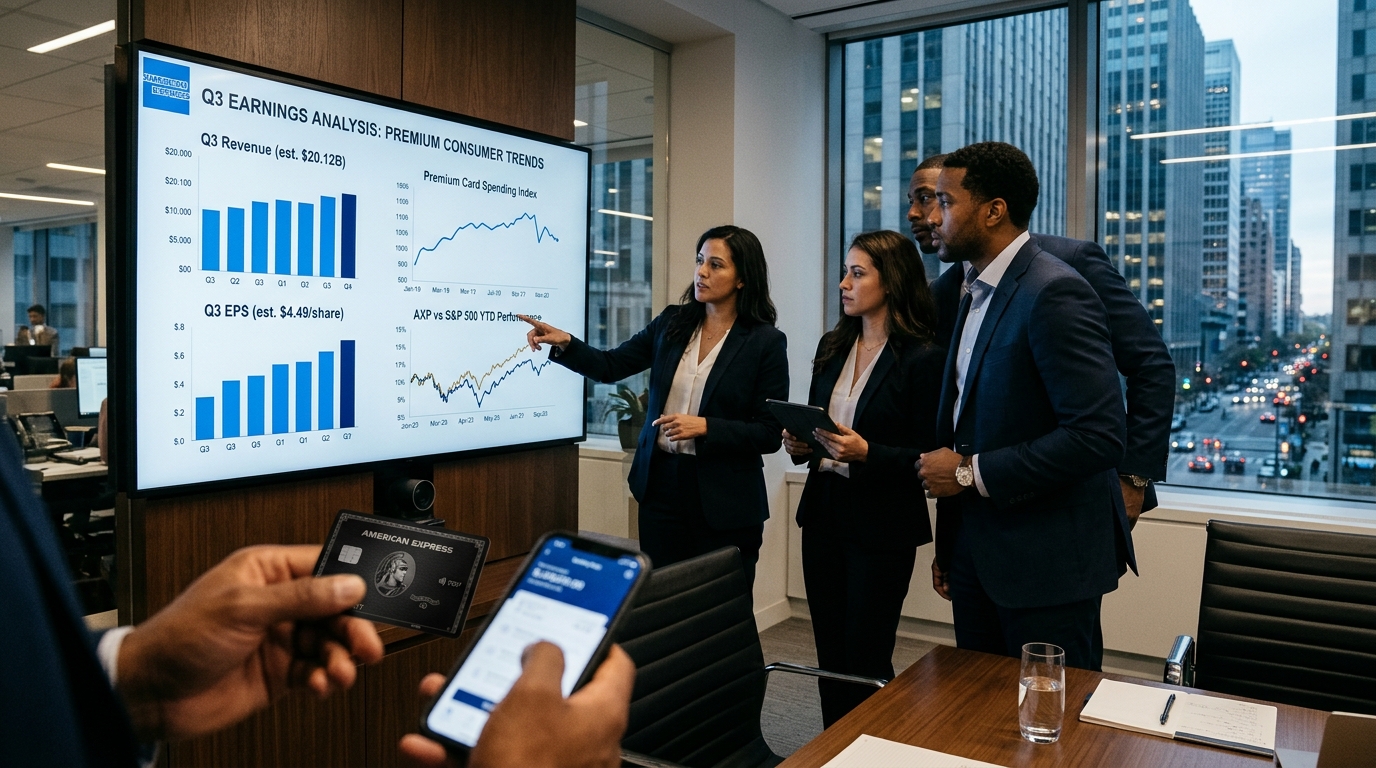
American Express is down roughly 12 percent year to date while the S&P 500 has gained more than 13 percent. That gap is the real question behind this morning’s number. The market has been pricing AXP not because the business is broken, but because it is betting that the affluent customer who carried spending through two years of rate pressure is finally starting to flinch. Today’s earnings report, before the open on October 23, is the most direct evidence yet on whether that bet is right.
American Express heads into Q3 2026 earnings with consensus estimates calling for earnings per share of $4.49 on revenue of $20.12 billion, against $4.08 per share a year ago, implying roughly 10 percent bottom-line growth. That is a reasonable bar, but the report lands the morning after the broadest risk-off session since July, which means the read on billed business growth will do more work than the EPS line itself.
The Business Behind the Card
American Express issues its own cards and runs its own payment network, so it earns annual fees from cardholders, swipe fees from merchants on every purchase, and interest on balances. That closed-loop model means billed business, the total spent on Amex cards, is both the engine and the early-warning system. In the first quarter of 2026, billed business grew 10 percent to $428.0 billion. In the second quarter it reached $455.8 billion, up 9 percent year over year. The trajectory has been solid; the question today is whether it held into July through September.
CEO Stephen Squeri called Q2 card member spending growth of 9 percent “the highest rate we’ve seen in three years on an FX-adjusted basis.” He also pointed to the Platinum portfolio as the fastest-growing in U.S. Consumer, with Millennials and Gen-Z cardholders representing a cohort the company describes as having greater lifetime value. That demographic bet is either a long-term advantage or a hidden cost, depending entirely on what rewards expense does to the margin.
The Swing Factor: Expenses
Revenue growth is not in dispute. The debate is what it costs to keep the premium card attractive. Second-quarter rewards expense rose 9 percent, cardholder-service costs jumped 50 percent, and total variable customer-engagement expenses increased 17 percent, outpacing revenue growth of 10 percent. Total expenses rose 12 percent to $14.5 billion in that quarter, with the Platinum refresh named as one driver.
Management has guided for variable customer-engagement expenses to represent 44 to 45 percent of 2026 revenue, with expense growth expected to slow from the fourth quarter as the Platinum refresh anniversary passes. If Q3 shows that slowdown beginning, the margin story flips positive. If it does not, the bear case gets louder.
One More Overhang
Regulators fined American Express National Bank $350 million over failures in anti-money laundering controls, saying about $13 billion in suspected trade-based money laundering activity over the past decade was not timely identified, evaluated, and sufficiently reported. The company said a portion of the penalty had already been reserved in prior periods and would not affect full-year 2026 guidance. With no asset cap imposed, the growth plan remains intact. The fine is a sideshow relative to billed business, but compliance remediation spending will be a question on this morning’s call.
Bull Case, Bear Case
Bull: BMO Capital Markets initiated coverage with an Outperform rating and a $380 price target, citing growth in the company’s premium-card ecosystem. At roughly 17 times forward earnings as of mid-October, Amex trades slightly below its five-year average P/E of 17.90, a discount applied to a business that just raised its full-year revenue guidance.
Bear: Concerns about declining consumer spending have weighed on the stock, even though American Express’s affluent customer base tends to be more resistant to inflationary pressures on expenses like gas and food. If billed business growth decelerates below 8 percent or the expense line surprises to the upside, the valuation premium over pure-play networks like Visa and Mastercard becomes hard to defend.
What to Watch
Three numbers decide the story today. First, billed business growth: anything at or above 9 percent confirms the affluent consumer is intact. Second, the variable expense ratio: a step toward management’s 44 to 45 percent target would signal Q4 margin relief. Third, guidance: after raising full-year revenue growth guidance to 10 percent in Q2, the company maintained EPS guidance of $17.30 to $17.90. Any move higher on EPS guidance this morning would be the catalyst the stock needs to close its gap with the broader market.
The affluent consumer has been AXP’s shield all year. This report tells us whether the shield still holds.